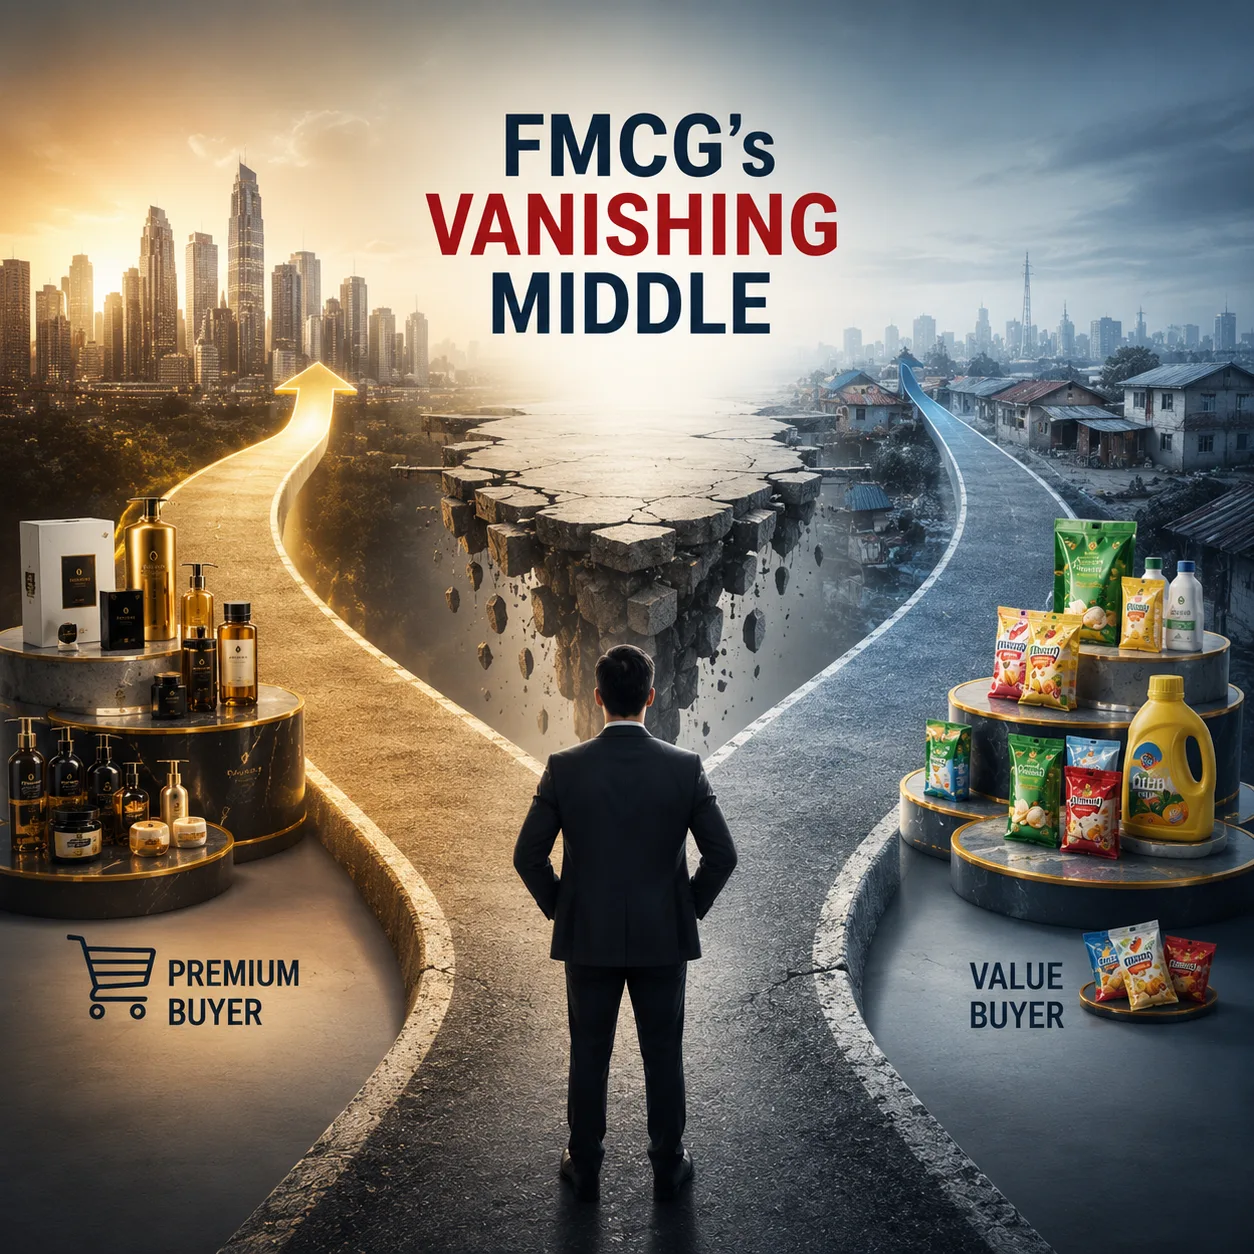

For a generation, the safest place for a consumer brand was the middle of the market: the familiar, mid-priced, national brand that most people bought without much thought. That position is now the most dangerous one to hold. Across the FMCG industry in India, and in the Gulf markets that mirror it, the mass shopper is separating into a premium buyer trading up and a value buyer trading down, and the brand in the middle is being deserted by both. This article explains why it is happening, why price is only part of the story, and what consumer leaders should do in the next three to five years.
What does the vanishing middle actually mean?

The middle is not an income group. It is a type of brand: neither the most distinctive nor the cheapest, the dependable default that once served almost everyone. Two forces are pulling shoppers away from it. At the top, premium and digital-first challengers win the affluent buyer on genuine distinctiveness. At the bottom, regional and value brands win on a real cost advantage. The mid-tier national brand is left competing for a shopper who is increasingly choosing one end or the other. The intellectual root of this is not new: the strategist Michael Porter called it being stuck in the middle back in 1980. What is new in 2026 is the machinery that now enforces that logic faster and far more harshly.
Is premiumisation the whole story? Not quite
It is tempting to read the vanishing middle as pure premiumisation, but the Indian data demands more discipline. NielsenIQ reported FMCG value growth of 12.9 per cent in the July to September 2025 quarter against volume growth of 5.4 per cent, with price growth of 7.1 per cent. A persistent gap of value over volume is the signature of a market where the average basket is getting more expensive. But it is not automatically proof of trading up, because that gap contains three different things: general inflation, pack-size reduction, and genuine shift to premium products. Only the third is premiumisation in any strategic sense.
The same data also describes a growing, competitive, volume-led market rather than a collapsing one. Rural volume grew faster than urban, and in the October to December 2025 quarter both cooled sharply as the GST 2.0 tax reset worked through the trade. So the mid-tier brand’s problem is competitive as much as it is positional. It is not only that shoppers are leaving the middle; it is that the middle is being out-fought within its own tier by nimbler rivals.
The clearest way to see the full picture is to ask where the pressure lands on a mid-tier brand’s profit and loss account. It lands on four fronts at once: the shopper, who is splitting into premium and value while health and the new weight-loss drugs reshape demand at the top; the shelf, where the channel shift and retail media decide what gets seen and what visibility costs; the cost base, where commodity cycles and compliance fall hardest on the brand with the least pricing power; and the rulebook, the wide field of tax and regulation, of which the GST reset is only the sharpest recent example, alongside packaging, labelling, advertising and data rules. Price is only part of the first front, which is why a leader who fixes only for price addresses a fraction of the problem.
How does quick commerce change which brands survive?

The single most overlooked force is the channel. The middle does not thin in the same way everywhere; it is squeezed differently in each channel, so a brand’s exposure depends on where it sells, not only on its price. In traditional kirana trade, which still carries the large majority of Indian FMCG, the mid-tier brand is outbid for the shelf by regional players rather than deserted by shoppers, and pack-size reduction lets it survive longer than expected. In modern trade, retailer private label brands displace the acceptable-quality middle cleanly, the pattern seen across Western grocery for two decades.
Quick commerce is different again, and it is the fastest. A dark store stocks a deliberately limited assortment, far smaller than a large supermarket, curated on local demand data. That assortment filter removes the sub-scale brands in every price band and keeps the category leader, so the weak middle brand is not rejected by shoppers, it is simply never shown to them. On top of this sits retail media: the platforms now charge every brand for visibility, transferring margin from brand to platform, and the mid-tier brand, with the least pricing power, feels that toll most.
How is the Gulf different from India?
The Gulf faces the same split from the opposite structure. India is a vast, price-sensitive market with only a thin premium top. The Gulf is a wealthy, premium-skewed market with almost no low-cost domestic base beneath it, and it is the state, through Saudi Vision 2030 localisation and food-security policy, that is now building that base. The regional food market is sizeable and growing steadily: Alpen Capital put GCC food consumption at 50.9 million tonnes in 2024, rising towards 55.5 million by 2029. For a company strong in India, the low-cost manufacturing skill honed at home is close to what the Gulf now needs, while the premium capability built for the Gulf raises the bar back in India. The two markets are best run as one connected system, provided the rules that do not travel, halal, Ramadan and market-by-market alcohol regulation, are respected locally.
What should consumer leaders do about it?
A brand caught in the middle has three ways out, and no fourth. It can move up into an earned premium, built on a genuinely better product or bought in by acquiring a challenger that already has it. It can move down into honest low cost, built on a real cost advantage rather than a national brand discounting itself. Or it can become the supplier and platform that the winners depend on, through private-label manufacturing, ingredients or distribution, trading margin for a defensible position. Staying in the middle and optimising it is not a strategy; it is a slow decline.
A practical sequence for the next three years
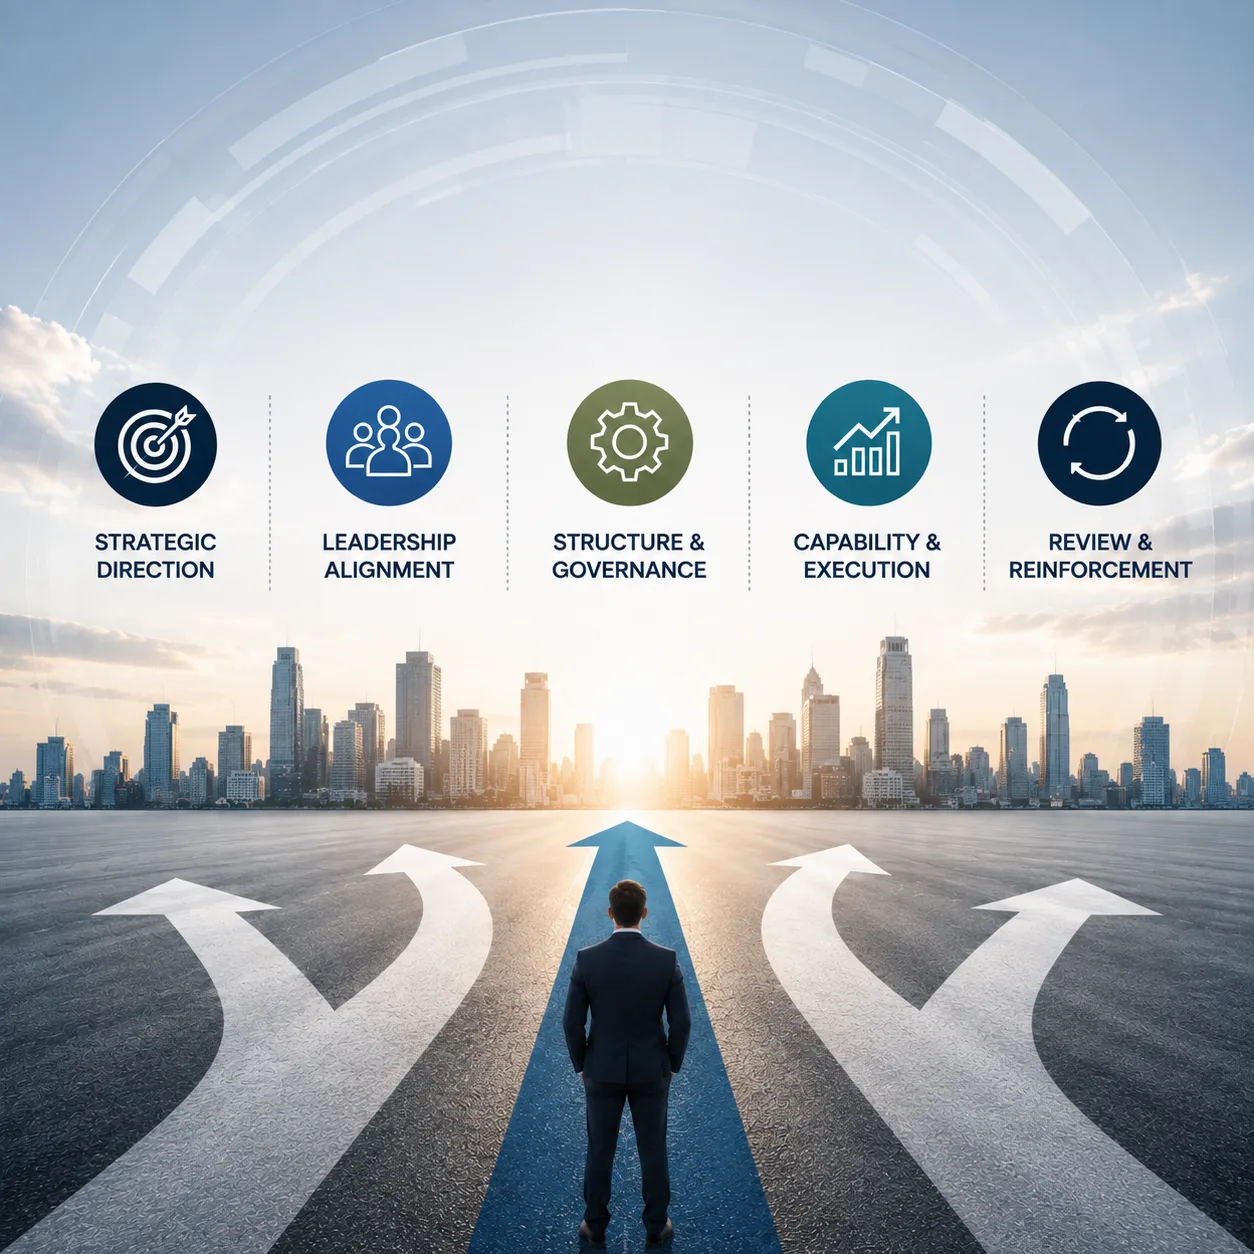
Start by diagnosing each brand honestly, and do it brand by brand and channel by channel, not across the portfolio as a whole. Ask four questions of each: does it have real pricing power, does it have a real cost advantage, what is its channel mix and how fast is each channel squeezing its tier, and is its recent growth genuine mix or just price and shrinking packs. The answers place each brand on one of the three paths. Then fund the move while the mainstream brands still generate the cash to pay for it, because that cash shrinks as the split widens, and own the decision at the top, since an organisation built for the middle will defend the middle if left to itself.
The takeaway
The vanishing middle is not a threat to be survived but a large market being reallocated, and it is already under way. The companies that win the market that emerges will be the ones whose leaders choose a clear end for each brand, diagnose exposure by channel rather than by price alone, and treat the change as an organisational task, not a marketing one. The decline of the middle is quiet, which is exactly the trap: it looks stable while it hollows out. There is still time to move, but not time to wait.
Planet Ganges helps consumer and retail leaders make exactly these portfolio and organisational choices. To discuss where your brands stand and which way out fits, explore our Business Transformation practice and start the conversation.
Frequently asked questions
What is the vanishing middle in the FMCG industry in India?
It describes how mid-priced mainstream brands are losing ground as shoppers move to premium or value, and as new channels and private label brands squeeze the middle. The brand position, not any income group, is what is at risk.
Is premiumisation good or bad for mid-market brands?
It is a threat if the brand cannot credibly move up. Premiumisation pulls the most profitable shoppers to distinctive brands, and a mid-tier brand that raises price without earning it strands itself faster than standing still would.
How does quick commerce affect FMCG brands?
Quick commerce stocks a limited assortment, so it concentrates demand on category leaders and filters out sub-scale brands regardless of price tier. Exposure to it should be measured brand by brand, because it moves faster than any other channel.